Engagement Ring Insurance in Australia: How to Insure Your Ring and What It Costs

By Jared James · Last updated 27 October 2026
Quick answer
There are three ways to insure an engagement ring in Australia: under your home contents policy up to its jewellery limit, listed as a specified item with portable cover, or with a specialist jewellery policy. Specialist cover costs about 1 to 2% of the ring's value a year, so roughly $40 to $80 for a $4,000 ring. Home policies cap unlisted jewellery at home: $1,000 per item or set with Budget Direct, $2,000 with AAMI, $2,500 for all jewellery and watches with NRMA and RACV, and $7,500 per item with Allianz. Every complete lab-grown ring we sell costs more than all but the Allianz limit, so it needs to be listed or covered by a specialist policy. Every price and limit on this page was checked against the insurers' own pages and PDS documents on 27 October 2026.
How do I insure an engagement ring in Australia?
There are three ways, and the right one depends on the ring's value and how often it leaves home with you. Your home contents policy covers jewellery at home up to a limit. Listing the ring as a specified item, with portable cover, insures it for its full value away from home too. A specialist jewellery policy, such as Q Report or Centrestone, covers the ring anywhere in the world and, where possible, repairs or replaces it through your own jeweller.
| Way to insure | At home | Away from home and overseas | Suits |
|---|---|---|---|
| Home contents, ring not listed | Up to the policy's jewellery limit, such as $1,000 per item or $2,500 for all jewellery | Usually not covered unless you add portable cover | A ring worth less than the limit that rarely leaves home |
| Home contents, ring listed with portable cover | Its full listed value | Covered away from home; overseas cover runs from 30 days to worldwide, depending on the insurer | Most engagement rings, if you want everything on one policy |
| Specialist jewellery policy | Its full insured value | Covered anywhere in the world | Higher-value rings, frequent travel, and replacement through your own jeweller |
What engagement ring insurance costs, by ring value
Specialist insurers price from the insured value, then adjust for postcode, cover level and excess. Centrestone publishes the estimates below as an overview of average costs in Australia. Comprehensive cover adds loss and theft to accidental damage, which is the cover most people mean when they insure an engagement ring.
Centrestone's own worked example covers a $15,000 engagement ring for $423.50 a year, with no excess and up to 150% cover. Q Report's page shows a $14,000 engagement ring at $385 a year before its one-time set-up fee of $126.50 per policy, or $46.46 a month with that fee included, plus a $10 application fee on the first instalment.
| Ring value | Basic cover per year | Comprehensive cover per year |
|---|---|---|
| $2,000 to $5,000 | $20 to $60 | $40 to $150 |
| $5,000 to $10,000 | $60 to $120 | $150 to $300 |
| $10,000 to $25,000 | $120 to $300 | $300 to $600 |
| $25,000 to $50,000 | $300 to $600 | $600 to $1,200 |
Is your ring already covered by home contents insurance?
Partly, and usually not for its full value. Home contents policies cap unlisted jewellery, and most only cover it at home unless you add portable cover. If your ring is worth more than the cap, list it as a specified item for its full replacement value, which adds to the premium. These are the limits the insurers publish, checked on 27 October 2026:
| Insurer | Unlisted jewellery limit | Cover away from home |
|---|---|---|
| AAMI | $2,000 per item or set, up to $5,000 in total, at home | Optional portable valuables cover: unspecified items up to $1,000 per item, pair, set or collection, or specify the ring for its full value. Outside Australia and New Zealand, only for 30 consecutive days while worn or in a secure safe |
| NRMA | Up to $2,500 for all jewellery and watches at home | Optional portable contents cover anywhere in the world, up to $10,000 per item unless listed, and $10,000 in total outside Australia and New Zealand |
| Allianz | $7,500 per item, set or collection at home; items worth more can be listed, but listed valuables are covered only at your address | Optional portable contents cover Australia-wide and for up to 90 continuous days overseas |
| RACV | Up to $2,500 for all jewellery and watches at home; optional Valuable Items Cover raises it, and any one item over $10,000 must be listed | Optional portable items cover for listed jewellery in Australia and New Zealand, up to $10,000 for all items overseas |
| Suncorp | Optional personal valuables cover: up to $1,000 per item, pair, set or collection, at or away from home in Australia and New Zealand | Specify an item to insure it for more than $1,000. Unspecified jewellery is covered elsewhere in the world for up to 30 consecutive days while worn or in a secure safe |
| Budget Direct | Up to $1,000 for any item or set, with a limit of $5,000 in total, unless specified | Optional personal effects cover, up to $1,000 per item unless specified, in Australia and New Zealand, and worldwide for up to 90 days after you leave |
| Youi | One total amount for jewellery; any piece, pair or set worth more than $15,000 must be specified | Optional accidental loss or damage cover, which extends worldwide |
How to find the jewellery limit in your PDS
The product disclosure statement (PDS) for your home contents policy sets how much it pays for jewellery, and the limit is easy to miss. Search the PDS for "jewellery", "valuables" or "portable", and check three things.
First, whether the limit is per item or a total for all jewellery. NRMA caps all jewellery and watches at $2,500 in total, so an engagement ring and a watch share that amount, while AAMI caps each item or set at $2,000 within a $5,000 total. Second, whether the cover applies only at home. Most policies cover jewellery away from home only if you add portable or personal valuables cover. Third, how to list a ring worth more than the limit, usually as a specified item with its own sum insured for an extra premium.
Does a Lily Dia ring need to be listed?
Yes, on almost every home policy. Our complete lab-grown rings start at $2,950 with a 1 carat stone in 18k gold, which is already more than AAMI's $2,000 per item or set, NRMA's and RACV's $2,500 for all jewellery and watches, and Budget Direct's $1,000 per item or set. A moissanite ring from $1,910 is above the $1,000 limits too. Allianz's $7,500 per item is enough for our 1 and 2 carat rings at home, but not for a 3 carat ring over $7,500, and none of these limits covers the ring on your hand away from home without portable cover.
So list the ring as a specified item for its full price, or insure it with a specialist. Current prices are on our 1 carat, 2 carat and 3 carat rings. Prices below were checked on 27 October 2026.
| Complete ring | 18k gold | Platinum |
|---|---|---|
| 1 carat IGI lab-grown diamond | $2,950 to $4,350 | $3,000 to $4,500 |
| 2 carat IGI lab-grown diamond | $4,250 to $5,950 | $4,300 to $6,100 |
| 3 carat IGI lab-grown diamond | From $6,900 | $6,950 to $10,700 |
Getting a valuation for your engagement ring
A valuation records what the ring is and what it would cost to replace. The National Council of Jewellery Valuers says a valuation contains a full description and a statement of its purpose and intended market, and recommends reassessing it every two or three years. Only its members can call themselves an NCJV Registered Valuer.
For a new piece, the Jewellers Association of Australia says a valuation certificate from the retailer is acceptable as long as it fully describes the item and shows the price you actually paid, and it recommends revaluing jewellery about every two years. Insurers use the valuation to set the sum insured and to settle a claim. AAMI, for example, asks for proof of purchase, a valuation from a qualified professional valuer and a close-up photograph for any item worth more than $3,000. For a new ring, the tax invoice and grading report usually set the value, then book a valuation as prices move.
Face up
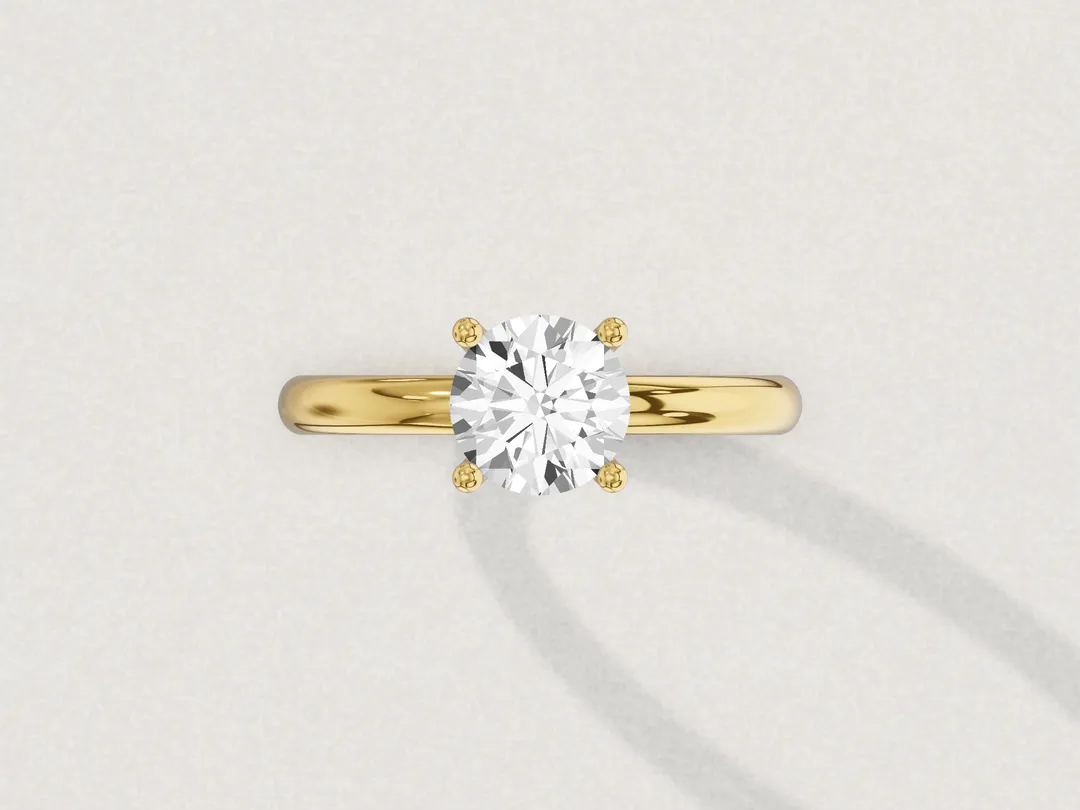
Face up: the diamond, its four claws and the top of the band.
Side
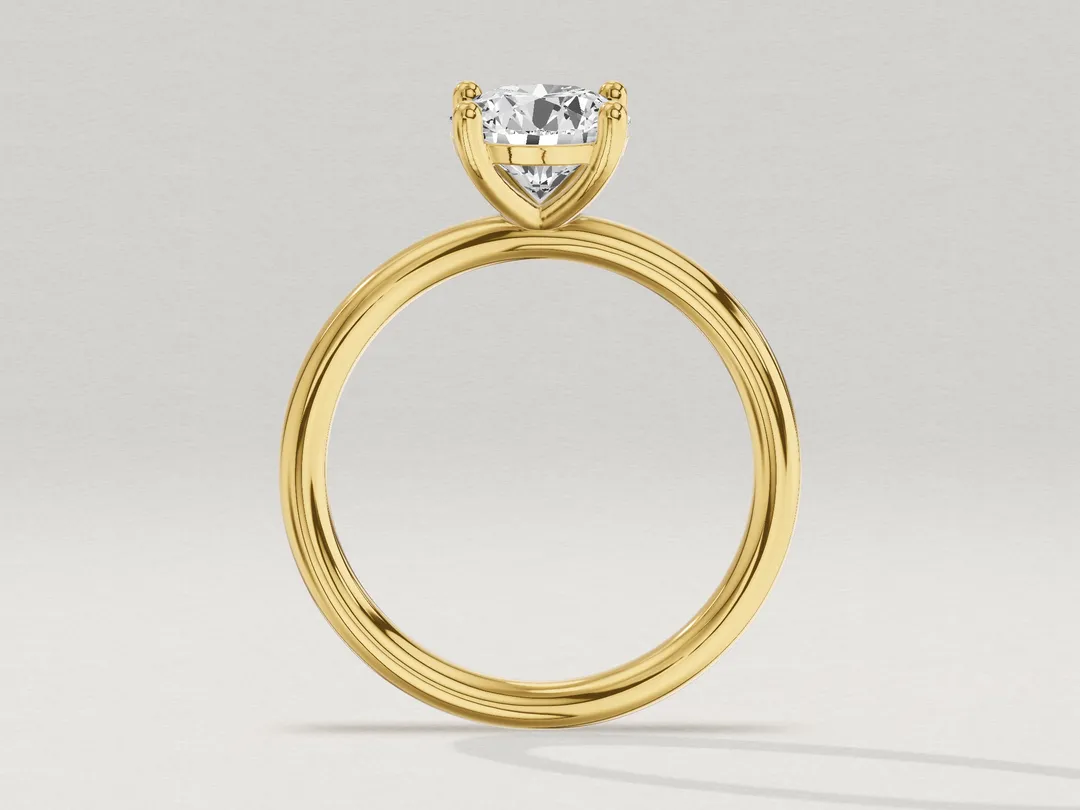
From the side: the head, the setting height and the shank.
What do we give you for the insurer?
The papers an insurer and a jeweller need to describe and remake the ring: your tax invoice describing it, the IGI report for a lab-grown centre stone with its report number and, for a custom ring, the approved CAD design. Keep copies with your policy schedule.
Our lifetime manufacturing warranty covers manufacturing defects for the original buyer. It does not cover loss, theft, accidental damage or normal wear, which is why the ring needs insurance.
Specialist policy vs home contents: what the PDS documents say
The two specialist jewellery insurers most Australians compare are Q Report, issued by Chubb, and Centrestone, underwritten by Berkley. The table sets them against a typical home contents specified item, using their provider pages and product disclosure statements as at 27 October 2026. Provider names are examples for comparison, not endorsements. NRMA also sells Single Item Insurance through Insurance4That, which covers one item for its full replacement value against listed events at home, with optional theft and damage cover elsewhere in Australia.
| Feature | Q Report (issued by Chubb) | Centrestone (underwriter Berkley) | Home contents specified item (typical) |
|---|---|---|---|
| Worldwide cover | Yes | Yes | Varies, from Australia and New Zealand only to worldwide with portable cover |
| Accidental loss | Yes (physical loss or damage anywhere in the world) | Yes | Depends on the policy and add-ons |
| Mysterious disappearance | Yes (product page) | Yes (product page) | Frequently excluded |
| Accidental damage | Yes | Yes | Depends on the policy |
| Choice of jeweller | Your original or preferred supplier where possible (PDS) | Your preferred jeweller | Usually the insurer arranges repair or replacement |
| Settlement | Like-for-like replacement at market value; if it costs more than the sum insured, up to 150% of it, capped at $50,000 above, for items insured at market value | Repair or replacement through your preferred jeweller, up to 150% of the sum insured; no cash payouts | Repair, replace or cash settlement |
| Excess | Fixed $100 advertised; the PDS calls it a deductible | No excess advertised; the PDS allows one in your schedule | Your home policy excess applies |
| Revaluation | Free revaluation at each renewal (product page) | Insured value set from the invoice or valuation | You update the specified amount yourself |
Loss outside the home and overseas
This is where the options separate most, because an engagement ring lives on a hand, not in a house. Both specialist policies cover the ring anywhere in the world. Home contents covers jewellery away from home only when you add a portable or accidental loss option, and the geography varies: AAMI covers jewellery outside Australia and New Zealand for 30 consecutive days while it is worn or in a secure safe, Allianz and Budget Direct for up to 90 days overseas, and NRMA portable contents and Youi accidental loss or damage extend worldwide. If you travel often, or the proposal is happening overseas, read that clause first.
Our guide to travelling with an engagement ring covers airport security, customs and where to keep it on the trip.
Agreed value vs replacement: how a claim actually pays
The settlement clause decides what a claim feels like. Q Report's market value cover is a like-for-like replacement from your original or a similar supplier, and if replacing the ring costs more than the sum insured, it can pay up to 150% of the sum insured, capped at $50,000 above it. Centrestone settles claims directly with your preferred jeweller, with up to 150% cover, and does not offer cash payouts. A home contents policy typically leaves the choice of repair, replacement or cash to the insurer.
For a made-to-order ring, replacement through your original jeweller is usually the outcome you actually want, because a cash figure does not rebuild a custom design. Either way, the number on the schedule should be the current replacement cost, not the historical purchase price.
Lab-grown diamonds: insure the replacement cost, not the mined price
Centrestone does not require an appraisal for a lab-grown diamond, because the purchase price usually reflects the current replacement cost, so a copy of the tax invoice is enough. Q Report says it revalues insured jewellery at each renewal at no charge, which matters more for lab-grown stones than mined ones. Neither provider publicly commits to replacing a lab-grown stone with a lab-grown stone of matching specification, so ask that directly and keep the answer in writing.
The revaluation direction usually surprises people. On our ring builder on 27 October 2026, a new 1, 2 and 3 carat IGI lab-grown stone started at $1,084, $2,206 and $2,512, and a typical stone cost $1,321, $2,600 and $4,088. Lab-grown prices have fallen for years, so a lab-grown ring is more likely to need its sum insured revised down than up, and revaluing stops you paying premiums on a replacement cost the market no longer charges. Do lab-grown diamonds hold their value? explains why.
Is a wedding band insured the same way?
Yes, through the same three routes, and check how the policy treats a pair or set before you list them. AAMI's at-home limit is $2,000 per item or set, so if it treats your engagement ring and wedding band as a set, they share one limit. Youi asks you to specify any piece, pair or set worth more than $15,000. On a claim for one ring, NRMA and Budget Direct cover only the item that was lost or damaged, while Q Report will replace a whole pair or set if you hand over the undamaged part.
List each ring with its own value, or the pair together, whichever your insurer asks for, and keep both invoices in the same file. If you're still choosing a band, we make wedding bands to sit with your ring.
What about other jewellery?
The same three routes cover earrings, necklaces, bracelets, watches and inherited pieces. Check whether the home limit is per item or for all jewellery together: NRMA and RACV cap all jewellery and watches at $2,500 in total, so a ring, a watch and a necklace share that amount. An inherited piece needs a written valuation, because there is no recent invoice to set its value, and the Jewellers Association of Australia recommends an NCJV registered valuer for pre-owned jewellery. The valuation should describe the metal, the stones and any grading reports, the setting, the measurements and the condition, with clear photographs.
Insure for replacement cost, not resale value. Replacement cost is what it would cost now to supply a comparable piece; resale value is what a secondhand buyer would pay you, which is usually lower, so a resale estimate should not be the insured amount. A piece insured for less than it costs to replace pays out only the insured amount. For a custom or inherited piece, ask how design details and stones that cannot be matched exactly will be handled.
What isn't covered?
Wear and tear and damage from cleaning or repairs are the common gaps, and each policy words them differently. Q Report's PDS does not cover "loss caused by wear and tear, gradual deterioration", or loss or damage "caused by the process of cleaning, repairing, refinishing". Centrestone's PDS excludes wear and tear, gradual deterioration, and loss or damage from cleaning, refinishing, repairs or alterations. NRMA says of its portable contents cover: "We don't cover scratches and dents or items being cleaned or repaired." AAMI's PDS doesn't cover contents that aren't in good condition, and its examples include rings "where the claw (surrounding the stone) is damaged or worn", which is one more reason to have the claws checked; our care and maintenance guide covers when.
None of the PDS documents we read has a separate exclusion for jewellery left unattended, though Centrestone's and NRMA's require you to take reasonable care of it. Centrestone also requires any item with set stones insured for more than $15,000 to be maintained by a JAA registered jeweller at least once every three years, at your expense. Allianz covers listed valuable contents only at your address, so a ring listed there needs portable cover to be insured on your hand.
How do you make a claim?
Report it, tell your insurer and send your file, in that order. This is what the insurers we checked ask for:
- Report a theft to the police as soon as you can and keep the report number. AAMI, NRMA, Q Report and Centrestone all ask for it.
- Tell your insurer straight away. Centrestone sets a limit of 30 days, and Q Report and AAMI ask to hear as soon as you can.
- Send proof of ownership and value. NRMA lists tax invoices, receipts, valuation certificates, bank statements and photographs. AAMI won't accept a statutory declaration as your only proof, while Centrestone asks for one alongside the invoice and a photograph.
- Don't have the ring repaired or replaced before the insurer agrees. NRMA's PDS requires its consent first.
- On a monthly specialist policy, expect to settle the rest of the year: Centrestone asks for the balance of the annual premium and the excess before it settles a claim.
Insure or self-insure: the five-year maths
Run the numbers for a $4,000 ring. On Centrestone's comprehensive estimate of $40 to $150 a year, five years of premiums comes to $200 to $750, plus any set-up fee and excess. Against that sits a $4,000 replacement if the ring is lost with no cover.
The answer depends on you. Insurance hands a rare but painful loss to an insurer, which is worth paying for when $4,000 is money you could not find at short notice. Self-insuring means keeping the full replacement amount available for the life of the ring, and accepting that a loss in the first year costs the whole amount. Neither choice is financial advice.
The documents to have ready before you need them
Every insurer we checked asks for proof you owned the ring and proof of what it was. Put this file together in the week the ring arrives and keep a copy in cloud storage: the tax invoice, a valuation certificate if you have one, clear photographs from the top and side, the grading report and its report number, and the design record for a custom ring. Add to it each time the ring is resized, reset or repaired, because each change can alter the description or the replacement cost. When you apply, Centrestone also asks for a proof of possession photo showing the ring held up in front of something displaying today's date.
At claim time, Centrestone asks for a tax invoice or receipt, a photograph and a statutory declaration of ownership, plus a police report number for theft or malicious damage. Q Report requires notice as soon as practical, police notification for theft, and a signed, sworn proof of loss within 60 days of a request. For an independent valuation, the National Council of Jewellery Valuers has a Find a Valuer search of its registered valuers. Australian law does not require a tertiary qualification in jewellery valuation, so a registered valuer is the safer choice.
Questions to ask before you buy, and when to revalue
Ask these against any quote, and check the answer in the PDS rather than the sales page: what is the per-item limit and the excess on my schedule; is the ring covered for accidental loss and mysterious disappearance, not just theft; am I covered worldwide, and for how long per trip; who chooses the repairing jeweller; is settlement replacement, agreed value or cash at the insurer's option; will a lab-grown stone be replaced like for like; how are a matching engagement ring and wedding band treated; what documents will you need at claim time; and how do revaluations work at renewal.
Then revalue the ring every two to three years, as the National Council of Jewellery Valuers recommends (the Jewellers Association of Australia suggests about every two), after any change such as resizing, resetting or adding a halo, and whenever the market moves your replacement cost noticeably in either direction. A schedule that drifts from reality fails both ways, costing too much premium or replacing too little ring.
This page is general information, not financial advice, and does not consider your circumstances. Premiums, limits and terms are as published on 27 October 2026 and change without notice. Always read the current PDS and target market determination before buying, and confirm any figure directly with the insurer.
Sources and PDS documents
- #01
Centrestone: how much does it cost to insure an engagement ring?
Estimated annual premiums by ring value, last updated 17 October 2025. Checked 27 October 2026.
- #02
Centrestone: the facts about jewellery insurance
The 1 to 2% guidance and the $15,000 ring at $423.50 a year. Checked 27 October 2026.
- #03
Centrestone lab-grown diamond insurance
No appraisal needed for lab-grown diamonds. Checked 27 October 2026.
- #04
Centrestone FAQ
Proof of possession photo, insured value and no cash payouts. Checked 27 October 2026.
- #05
Centrestone PDS and policy wording (V20210921)
Settlement, excess, exclusions and claim documents. Still the PDS linked from Centrestone on 27 October 2026.
- #06
Q Report engagement ring insurance
Example premiums, set-up fee, fixed excess and revaluation at renewal. Checked 27 October 2026.
- #07
Q Report FSG and PDS (16 October 2026)
Settlement basis, deductible, exclusions, pairs and sets, and claim requirements.
- #08
AAMI guide to engagement ring insurance
Home contents jewellery limits and portable valuables cover. Checked 27 October 2026.
- #09
AAMI home and contents insurance PDS
Jewellery limits, portable valuables, the 30-day overseas condition, exclusions and claim proof. Prepared 4 October 2024; still current on 27 October 2026.
- #10
NRMA Insurance jewellery insurance
Home contents jewellery limit, portable contents cover and Single Item Insurance. Checked 27 October 2026.
- #11
NRMA home insurance PDS
Jewellery and watches limit, portable contents, pairs and sets, and claims. Prepared 10 September 2023. Checked 27 October 2026.
- #12
Allianz: insurance cover for your jewellery
Per-item limit, listed valuable contents and overseas portable cover. Checked 27 October 2026.
- #13
RACV jewellery insurance guide
Jewellery limit, listing threshold and portable items cover. Checked 27 October 2026.
- #14
Suncorp personal valuables
Unspecified item limit and overseas conditions. Checked 27 October 2026.
- #15
Budget Direct: engagement ring insurance
Jewellery limit per item or set at home. Checked 27 October 2026.
- #16
Budget Direct personal effects cover
Per-item limit, pairs and sets, and overseas cover period. Checked 27 October 2026.
- #17
Youi: jewellery insurance for engagement rings
Specified jewellery threshold and worldwide accidental loss cover. Checked 27 October 2026.
- #18
National Council of Jewellery Valuers: valuation and assessment
What a valuation contains, reassessment every two or three years, and qualifications. Checked 27 October 2026.
- #19
National Council of Jewellery Valuers: find a valuer
The register of NCJV valuers and how to check membership. Checked 27 October 2026.
- #20
Jewellers Association of Australia: value and insure
Retailer valuation certificates, pre-owned jewellery and revaluing about every two years. Checked 27 October 2026.
- #21
Moneysmart: contents insurance
Item limits, avoiding underinsurance and adding special items. Checked 27 October 2026.
Frequently asked questions
- Is it worth insuring an engagement ring?
- Usually, yes. Every complete lab-grown ring we sell costs more than most home policies' unlisted jewellery limits, and those limits usually apply only at home. Specialist cover is about 1 to 2% of the ring's value a year, so the real question is whether you could replace the ring yourself if it were lost.
- How much does engagement ring insurance cost in Australia?
- Specialist insurers put it at about 1 to 2% of the ring's value a year. Centrestone's published estimates run from $40 to $150 a year for comprehensive cover on a $2,000 to $5,000 ring, its own example covers a $15,000 ring for $423.50 a year, and Q Report's page shows a $14,000 ring at $385 a year. Your quote depends on postcode, cover level and excess. Figures checked 27 October 2026.
- How much does it cost to insure a $10,000 ring?
- About $100 to $200 a year at 1 to 2% of its value. Centrestone's estimates for a $5,000 to $10,000 ring are $60 to $120 a year for basic cover and $150 to $300 a year for comprehensive cover. A home contents policy would need the ring specified, because a $10,000 ring is well above the usual unlisted jewellery limit.
- Is it worth insuring a $3,000 engagement ring?
- Usually, yes, because a $3,000 ring sits above most unlisted home contents limits, such as $2,000 per item or set with AAMI and $2,500 for all jewellery with NRMA, and those limits usually apply only at home. Comprehensive specialist cover for a ring at that value is estimated at $40 to $150 a year.
- Does home contents insurance cover jewellery in Australia?
- Yes, up to a limit, and usually only at home. AAMI covers $2,000 per item or set, NRMA and RACV $2,500 for all jewellery and watches, Budget Direct $1,000 per item or set, and Allianz $7,500 per item, set or collection. A ring worth more needs to be listed, and away from home it needs portable cover.
- Do I need a separate policy or can I add the ring to home insurance?
- Either works. Specifying the ring on home contents is simpler and uses your existing excess, but check whether it is covered away from home and overseas. Specialist jewellery policies include worldwide cover, accidental loss and your choice of repairing jeweller where possible. Compare the PDS wording, not the marketing summary.
- When should I insure an engagement ring?
- As soon as you have it, and ideally before the proposal. In the same week, put together the claim file: receipt, valuation or grading report, and photographs. Loss can happen at any time and policies are not backdated.
- How often should jewellery be revalued?
- Every two to three years, as the National Council of Jewellery Valuers recommends; the Jewellers Association of Australia suggests about every two. Revalue sooner after a resize, a reset or a big move in prices.
- Are lab-grown diamond rings insured differently?
- The cover works the same way, and Centrestone insures lab-grown rings from the purchase invoice without an appraisal. Because lab-grown prices have fallen over time, revalue regularly so you are not paying premiums on an outdated replacement cost, and ask the insurer in writing whether a replacement will match the stone.
- Is a lab-grown diamond ring cheaper to insure?
- Usually, because premiums follow the insured value, and a lab-grown ring costs less to replace than a mined diamond ring of the same size and grade.
- Does Lily Dia's warranty cover loss?
- No. Our lifetime manufacturing warranty covers manufacturing defects for the original buyer. Loss, theft, accidental damage and normal wear are not covered, which is why we recommend insuring your ring.